Crypto FBAR Rules 2026: Do Foreign Exchanges Count?

 Expert verified
TokenTax content follows strict guidelines for editorial accuracy and integrity. We do not accept money from third party sites, so we can give you the most unbiased and accurate information possible.
FinCEN Notice 2020-2: crypto alone is not currently an FBAR-reportable account (FinCEN intends to change this).
Fiat in a foreign account can count toward the $10,000 aggregate FBAR test.
FBAR for calendar year 2026 is due April 15, 2027, with an automatic extension to Oct. 15, 2027.

Why trust our crypto tax experts
Last reviewed: November 14th, 2026
Do foreign crypto exchanges require an FBAR in 2026?
Crypto on a foreign exchange doesn't currently require an FBAR on its own.
Under FinCEN Notice 2020-2, virtual currency held in a foreign account is not itself an FBAR-reportable account today, though FinCEN has said it intends to amend the rules. Fiat currency in the same foreign account can count toward the $10,000 aggregate test. File any required FBAR for calendar year 2026 (filed in 2027) by April 15, 2027 (automatic extension to Oct. 15, 2027).
What is the FBAR?
Crypto on a foreign exchange doesn’t require an FBAR on its own. Under FinCEN Notice 2020-2, an account holding only crypto isn’t reportable, but an account that also holds fiat or other reportable assets may be once your foreign accounts exceed $10,000 combined. FBARs for 2026 accounts are due April 15, 2027, with an automatic extension to October 15, 2027.
FBAR stands for Report of Foreign Bank and Financial Accounts, which you file on FinCEN Form 114.
The FBAR is designed to track foreign financial assets to prevent crimes like tax evasion. It applies to any US person whose foreign financial accounts were worth more than $10,000 combined at any point during the calendar year, and it reports each account’s highest balance for that year.
Although it has tax implications, the report itself is not filed with the IRS but rather with the US Treasury Department through the Bank Secrecy Act's e-filing system.
Do you report crypto on FBAR?
Under FinCEN Notice 2020-2, a foreign account holding only virtual currency is not a reportable account. That notice is still in effect, and FinCEN has not issued the rule it said it would propose to make virtual currency reportable on the FBAR. You report crypto on an FBAR when it sits in an overseas account that also holds other reportable assets, such as fiat currency or securities, and the aggregate threshold is met.
For example, if a US taxpayer converts cryptocurrency into foreign currencies held in the same account (and the aggregate value of these foreign currencies surpassed $10,000 at any point during the calendar year), the taxpayer would be obligated to declare the complete account value, including cryptocurrency holdings.
If you're not sure whether a foreign account also holds fiat or other reportable assets, check with a tax professional before deciding whether to file.
What is the deadline for filing my FBAR?
For 2026 accounts, the FBAR is due April 15, 2027, with an automatic extension to October 15, 2027 that you don’t need to request, per the IRS and FinCEN. You file it separately from your income tax return, through FinCEN’s BSA E-Filing System rather than with the IRS.
Is a cryptocurrency FBAR required?
As noted, the FBAR is required for US taxpayers whose foreign accounts holding fiat or other reportable assets, alone or alongside crypto, total over $10,000 at any point in the calendar year. While this affects a relatively small number of cryptocurrency investors and businesses, the obligation to submit IRS Form 8938 has a broader scope.
This obligation, established under the Foreign Account Tax Compliance Act (FATCA), encompasses a wider range of "foreign financial assets" beyond just offshore accounts.
Form 8938 (FATCA) is filed with your US tax return to report specified foreign financial assets when you exceed the applicable thresholds. Whether a particular crypto holding is reportable on Form 8938 depends on the facts, including what you own and how it’s held, because Form 8938 reporting is tied to “specified foreign financial assets” as defined in the instructions.
FATCA reporting thresholds and reporting
The rules depend on your filing status and whether you live abroad, and each status has both a last-day and an anytime threshold. If you live in the US and are unmarried or married filing separately, you file Form 8938 if specified foreign financial assets are more than $50,000 on the last day of the tax year or more than $75,000 at any time during the year. If you file jointly, those amounts are $100,000 and $150,000. If you live abroad and are unmarried or married filing separately, the thresholds are $200,000 for the last day of the tax year or $300,000 at any time; if you file jointly, they are $400,000 and $600,000. See the IRS comparison of Form 8938 and FBAR requirements, as well as the Instructions for Form 8938.
Living abroad means your tax home is in a foreign country and you're either a US citizen who was a bona fide resident of a foreign country for a full tax year, or a US citizen or resident present in a foreign country at least 330 full days in a 12-month period ending in the tax year.
If you're abroad and married, you must file Form 8938 if your combined foreign financial assets are over $400,000 at the end of the tax year or over $600,000 at any time during the year, even if only one spouse lives abroad.
Those living in the US must file if they are unmarried and their foreign financial assets exceed $50,000 at the end of the tax year or $75,000 at any time during the year. If you're married and filing jointly, the thresholds are $100,000 for the tax year or $150,000 at any time during the year.
If married and filing separately, include one-half the value of jointly owned assets when calculating the thresholds. If you meet the filing requirements, report the entire value on Form 8938.
How to file a crypto FBAR in four easy steps
These steps apply only if you have a reportable foreign account, such as an overseas account that also holds fiat or other reportable assets, and your foreign accounts totaled more than $10,000 at any point in the calendar year. A foreign account that holds only virtual currency is not reportable under FinCEN Notice 2020-2.
Here are four steps for filing a required FBAR. When in doubt, our crypto tax professionals at TokenTax can assist.
1. Use crypto tax software to organize your transactions
If you’ve traded on multiple exchanges, it may be helpful to use crypto tax software to aggregate and organize all your accounts so you can determine if and what you need to report. The Pro and VIP plans include FBAR.
If you are using TokenTax and have access to our FBAR feature, you will receive a report showing the highest balance you held in foreign accounts during the calendar year.
If you are already a Basic or Premium user and need to purchase the FBAR add-on, you can do so at the checkout page. Be sure that you've uploaded all your crypto data, including deposits and withdrawals for all exchanges. You can then generate your FBAR report on your Documents page and use it to file FinCEN Form 114 through the BSA E-Filing System.
2. Fill out your personal information on FinCEN's e-filing site
Individuals can use the Bank Secrecy Act (BSA) e-filing system to report their FBAR. FBARs should be filed by the April 15 tax deadline or by the October 15 tax extension deadline.
If an investor fails to file by April 15, they'll be granted an automatic extension, so there’s no need to file for any kind of FBAR extension.
In Part I of the e-filing process, fill out your personal information.
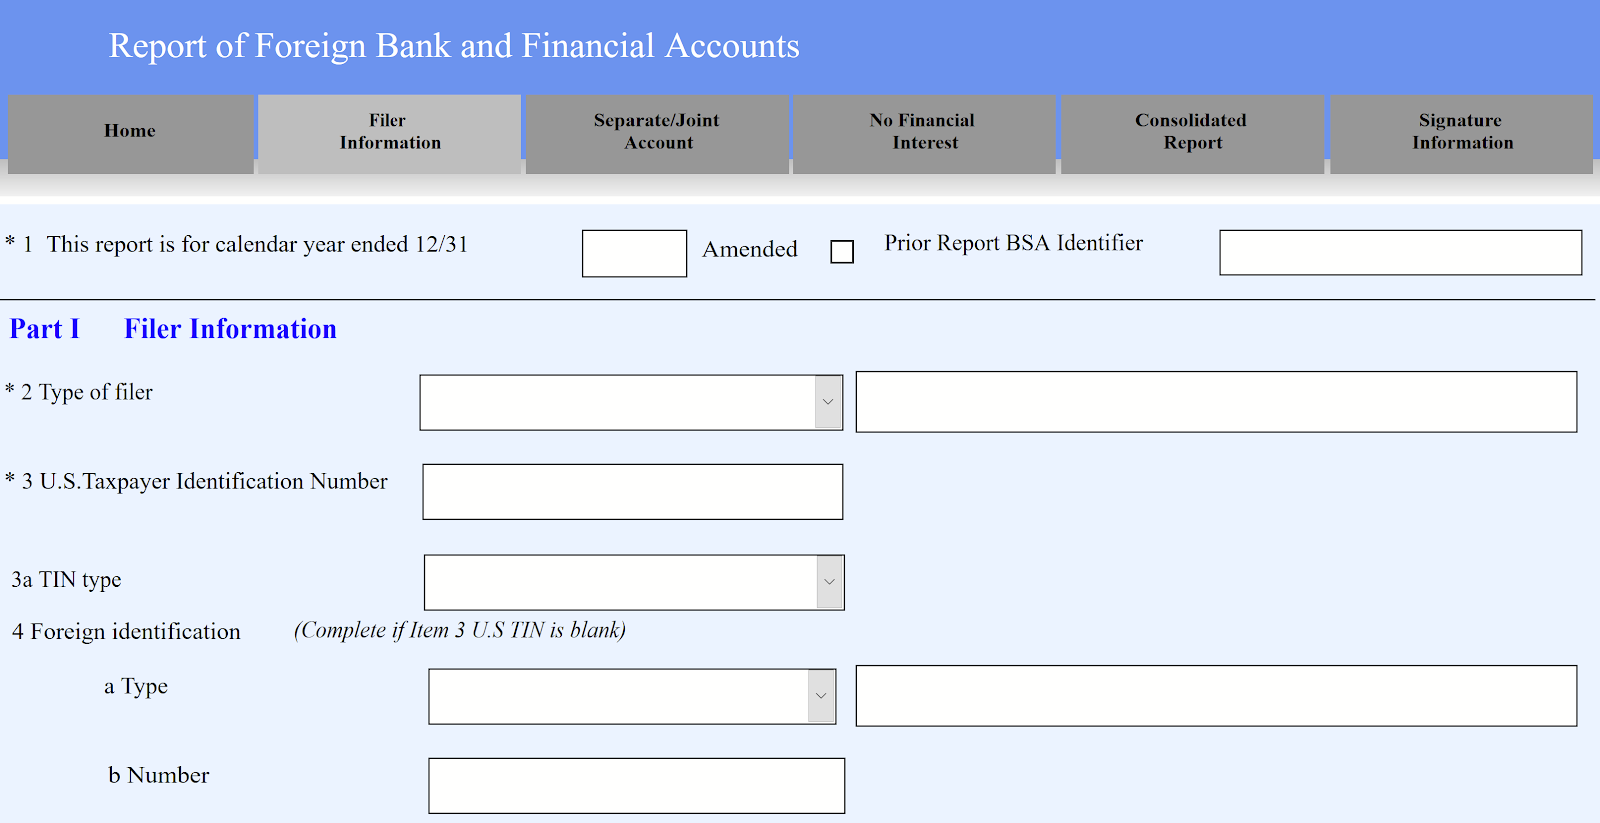
3. Provide information about the foreign crypto exchanges you've used
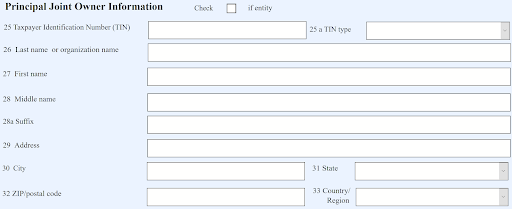
In either Part II or Part III, provide information about the foreign accounts you are required to report (for example, a foreign exchange account that also holds fiat or other reportable assets). Use Part II for accounts you own on your own and Part III for accounts you own jointly with someone else. If you have signature authority over an account but no financial interest in it, use Part IV.
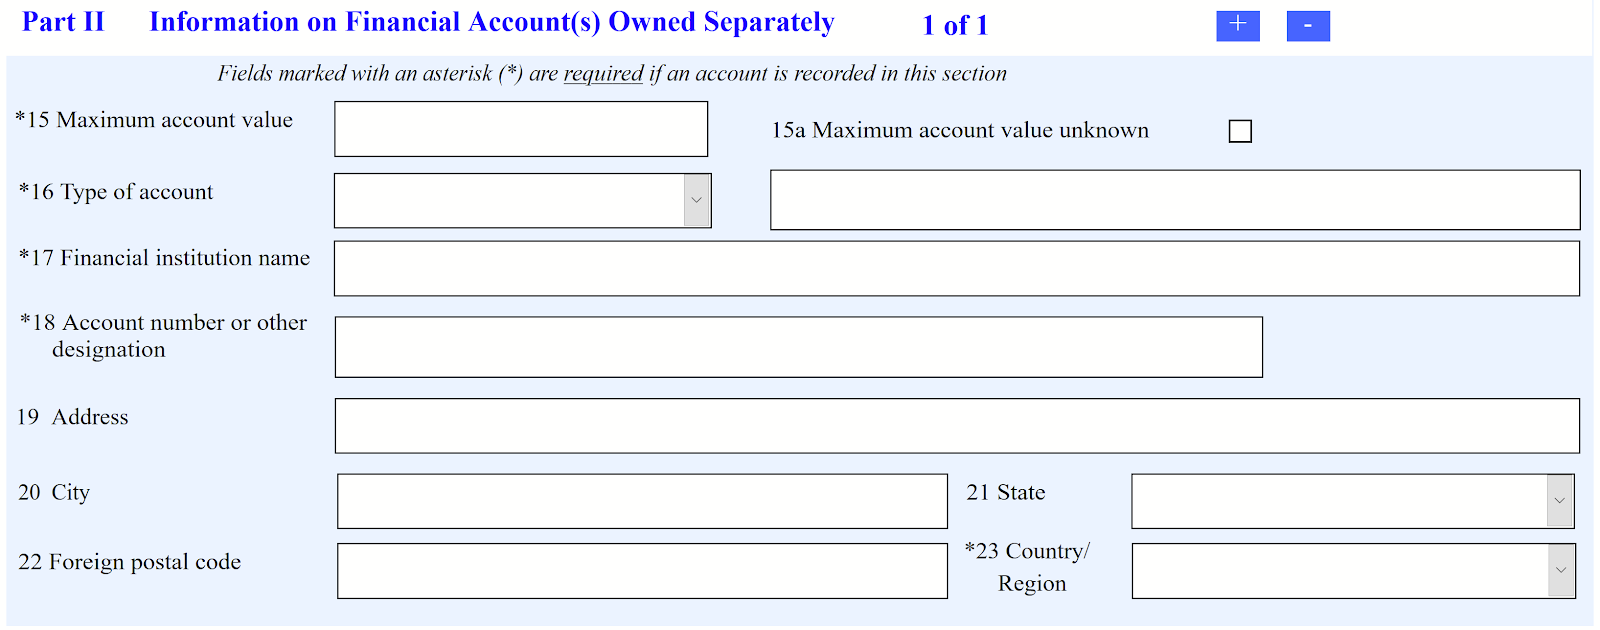
If you need to report multiple exchanges, you can create copies of the form by clicking the + box at the top of the form in Pt II or III.
4. Enter the account balance details for each exchange
For each exchange, here's how we typically fill out the FBAR for TokenTax customers:
On the top row of your TokenTax-generated FBAR report, you'll see the maximum account value. Enter this in the applicable field on the BSA e-filing site.
For "Type of account," select "Other" and then in the box to the right, type in "Cryptocurrency exchange."
For "Financial institution name," enter the name of the exchange.
For "Account number or other designation, " enter the email address used for the exchange login.
For the exchange's physical address, fill it out to the best of your ability. Some exchanges share their addresses, while others keep them secret for security reasons. At a minimum, the exchange's country should be entered. You can find a list of popular foreign exchanges' countries below.
Parts IV (signature authority only) and V (consolidated reports for entities) are typically left blank for individual account owners.
Finally, add your signature to the document and submit.
What do I need to file the FBAR?
Per the IRS, for every account requiring an FBAR report, taxpayers are required to maintain records containing the following details:
Account holder's name
Account number
Foreign bank's name and address
Account type and highest value reached within the year
The legislation does not stipulate a specific document type to accompany this information. Documents such as bank statements or a duplicate of a submitted FBAR with the necessary details could suffice.
Typically, these records should be retained for a period of five years from the FBAR's due date.
What is the Form 8938?
The 8938 is similar to the FBAR. It is a form that is reported to the IRS on your tax returns, while the FBAR is filed with FinCEN. The 8938 also has different, higher reporting thresholds, as set in the Foreign Account Tax Compliance Act (FATCA).
Read the IRS's summary of FATCA reporting for more information. Note that if you file a Form 8938, you may still need to file an FBAR as well. For more detailed information on the differences between the two forms, the IRS provides a table comparing Form 8938 and the FBAR.
Is a Form 8938 required for cryptocurrency?
The IRS has not provided specific guidance on whether FATCA applies to crypto held with foreign financial institutions, such as cryptocurrency exchanges, so whether you need to report a holding on Form 8938 depends on the facts. Some taxpayers choose to include crypto on Form 8938 in case later guidance requires it; talk to a tax professional before deciding.
Who needs to file an FBAR?
FBAR obligations extend beyond US citizens and cover "United States persons," a category that includes:
US citizens
US residents, including green-card holders and individuals who meet the substantial presence test
Entities created, organized, or formed under US law, including corporations, partnerships, limited liability companies, trusts, and estates
Per the IRS, any of these US persons must file an FBAR to report if:
They have a financial interest in or signature or other authority over at least one financial account located outside the United States and if:
The aggregate value of those foreign financial accounts exceeded $10,000 at any time during the calendar year reported.
What happens when I don’t file my FBAR?
In Bittner v. United States (2023), the Supreme Court held that the non-willful penalty applies per report rather than per account, sharply reducing exposure for anyone with multiple foreign accounts.
The current maximum for a non-willful violation is $16,536 per annual report. Willful violations are the greater of $165,353 or 50% of the account balance, assessed per account, per year, and they stack across years. Most FBAR cases are fought over which classification applies.
One exception worth knowing: no non-willful penalty applies if the violation was due to reasonable cause and the account balance was properly reported (31 U.S.C. § 5321(a)(5)(B)(ii)). That is a facts-and-circumstances test, not an automatic waiver for anyone who reported their crypto gains, and it does not apply to willful violations.
If the IRS has not contacted you about a late FBAR and you are not under a civil or criminal investigation by the IRS, file late FBARs as soon as possible to minimize potential penalties. On FinCEN's form, select a reason for filing late, or choose "Other" and explain.
If you are using a compliance option such as the Streamlined filing compliance procedures, follow those instructions instead.
How TokenTax can help with filing your FBAR
TokenTax simplifies the process of filing your FBAR as part of our comprehensive crypto tax solutions. Our crypto tax professionals are available to help with all aspects of your crypto tax needs, ensuring accurate, complete US filings regardless of how you use crypto.
Here are some of the ways we make crypto tax filing easy:
Easy Data Import
Sync your data seamlessly by connecting TokenTax to your wallets and accounts. This integration minimizes manual data entry, allowing you to consolidate and analyze all your crypto-related information in a single location. Our system supports various integrations, including those for DeFi, NFTs, margin, and futures trading.Tax Reports
Gain real-time insights into your tax liability with our comprehensive tax reports. These reports encompass multiple tax calculation methods, such as FIFO, LIFO, and Minimization (specific identification methods for US filers), as well as average cost for UK and Canadian filers. Additionally, you can access features like tax loss harvesting dashboards, mining and staking income reports, and Ethereum gas fee reports.Crypto Tax Forms
Our software automatically generates all the necessary tax forms, including Form 8949, Schedule D, and FBAR. These forms are crucial for completing your tax filings accurately, whether you choose to file with TokenTax or use another provider like TurboTax.Reconciliation
For investors with more intricate accounting needs, we offer advanced reconciliation services handled by knowledgeable crypto tax professionals. We're equipped to manage complex scenarios, such as missing cost basis data, high transaction volumes, and cross-chain transactions.Enterprise Solutions
If you require enterprise-level crypto tax solutions, we have tailored options available to meet your specific needs.
Ready to get started? Explore our plans and pricing to find a plan that fits your filing needs. With TokenTax, you can streamline your FBAR filing process and stay aligned with crypto tax reporting rules.
Which exchanges are not US-based?
You'll need to know which exchanges qualify as foreign financial institutions if you file an FBAR. Here is a list of exchanges outside the United States.
Common foreign exchanges
Binance (United Arab Emirates)
Bitfinex (British Virgin Islands)
bitFlyer (Japan)
Bithumb (South Korea)
BitMEX (Seychelles)
Bitstamp (Luxembourg)
BTC Markets (Australia)
Bybit (United Arab Emirates)
CEX.IO (St. Kitts and Nevis)
Deribit (United Arab Emirates)
Gate (Cayman Islands)
KuCoin (Turks and Caicos Islands)
OKX (Seychelles)
Poloniex (Panama)
Common US exchanges that do not need to be included on the FBAR
Here is a list of the most common US-based exchanges. These do not need to be included on the FBAR.
Cash App
Gemini
Kraken
DeFi exchanges
Many DeFi protocols aren't registered in any country, and neither the IRS nor FinCEN has said whether, or how, DeFi positions count for the FBAR or Form 8938. If you hold significant assets in DeFi, check with a tax professional.
FBAR for crypto FAQs
What is the FBAR, and who needs to report foreign financial accounts?
Do I need to report joint ownership on an FBAR for crypto?
How do I report cryptocurrency to the IRS?
What happens if I don't report cryptocurrency on taxes?
Is crypto subject to FBAR?
Does FATCA apply to crypto?
Does the IRS look at crypto?
Is cryptocurrency considered a foreign asset?
To stay up to date on the latest, follow TokenTax on Twitter @tokentax.
Related Content
